



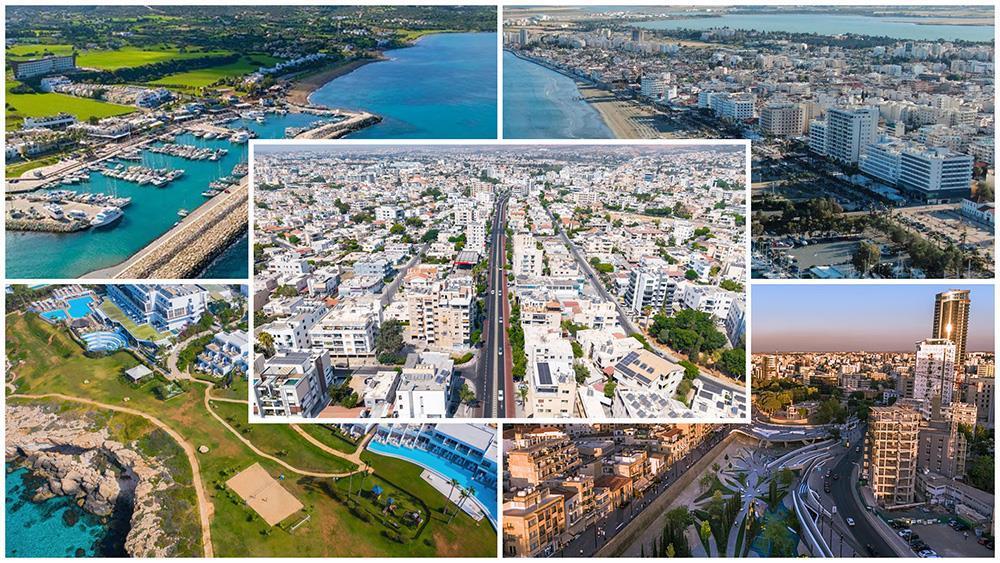
The substantial change in the new housing market in the third quarter of 2026 is not limited to the increased number of registered sales documents. It is also found in the redistribution of the share between districts, price categories and individual markets.
Landbank Analytics' new comparative analysis examines 1,956 sales of apartments and houses under construction or in the planning stage, with a total value of €606.4 million, and compares the third quarter with the second quarter of 2026. It highlights where recorded activity increased, which markets gained share and which areas combine transaction volume and high values.
More operations, different distribution
In the second quarter, 1,317 sales documents were recorded with a total value of €400.1 million. In the third quarter, the number rose to 1,956 and the value to €606.4 million, recording an increase of 48.5% and 51.6% respectively. The data for the second quarter reach up to 29 June, while those for the third quarter cover up to 30 September. Therefore, the changes concern the recorded activity and not automatically an equivalent change in final demand.
The average value per sales document was €310,019 from €303,808, an increase of 2.0%. For apartments, the average value was €269,217 and the median was €214,500, while for houses the average value was €478,138 and the median was €380,000. The composition of the sample affects these prices; they are not an indicator of the change in the price of comparable properties.
Limassol returned to the forefront of value
Limassol gathered 599 sales outlets worth €245.3 million. Its share in the number of transactions increased from 26.3% to 30.6%, while its share in value from 32.4% to 40.5%. Paphos also strengthened its position: its share in transactions increased from 12.8% to 17.0% and its share in value from 21.2% to 22.0%.
In contrast, Nicosia fell from 34.5% to 25.0% of transactions, despite recording 489 sales. Larnaca essentially maintained its share in terms of numbers, at 24.0%, while Famagusta accounted for 3.4%. Changes in shares do not equate to changes in absolute activity.
The segment below €300,000 maintains the greatest weight
Sales with a value of less than €300,000 amounted to 1,267, representing 64.8% of the transactions recorded in the third quarter. The corresponding share in the second quarter was 68.1%. Although the participation of the lower and middle segments decreased by 3.3 percentage points, it still accounts for almost two out of three transactions.
The largest category was €200,000–€299,999, with 545 transactions and a 27.9% share. This was followed by €300,000–€499,999 with 521 sales and 26.6%. The categories €150,000–€199,999 and under €150,000 participated with 21.4% and 15.5%, respectively.
These changes reflect the composition of sales by price category and not necessarily price changes. The picture is particularly useful for product design and pricing policy of new developments.
The most active areas of the third trimester
Based on the number of registered sales, the city of Limassol remained first with 190 transactions, up from 129 in the second quarter. The city of Larnaca followed with 124, Lakatamia with 111 and Aradippou with 109. The city of Paphos recorded 96, Strovolos 90, Livadia 79 and Germasogeia 73.
The comparison indicates a notable increase in recorded activity in Limassol City, Paphos, Strovolos and Germasogeia. However, the absolute number of sales documents is not enough to evaluate an area: the median value and the composition of properties complete the picture.
Areas that gained volume and areas that maintained their position
The city of Limassol increased its recorded transactions from 129 to 190 (+47.3%), while Larnaca from 71 to 124 (+74.6%). Germasogeia from 43 to 73 (+69.8%) and Strovolos from 71 to 90 (+26.8%). Lakatamia increased from 92 to 111 (+20.7%).
Aradippou is a different case: recorded transactions decreased from 122 to 109 (−10.7%), but it continued to be in the top four in absolute volume. The examples highlight why the most active areas should be evaluated both in terms of the number and the change in their transactions.
Germasogeia and Agios Tychonas on the premium map
Germasogeia recorded 73 sales worth €44.8 million in the third quarter, with an average value of €613,991 and a median of €383,762. From the 43 transactions in the second quarter, it increased by 69.8%, maintaining a significant presence in the high-value real estate markets.
In Agios Tychonas, 16 transactions were recorded with a total value of €18.1 million, with a median of €647,123 and an average value of €1,129,796. The high average value reflects the weight of the most expensive transactions and should be interpreted in conjunction with the median and the individual ranges.
Peyia, which had a particularly high median value in Q2, recorded 34 sales in Q3, worth €16.1 million, with a median of €398,000. Therefore, the rankings of premium areas vary significantly from quarter to quarter and conclusions of a general decline or rise in prices should not be drawn from the sales mix alone.
The combination of number of sales, lowest, median, average and highest recorded value allows for a more complete representation of the local market. Individual large value transactions can significantly move the average, without changing the typical transaction accordingly.
Andreas Christoforidis: "The market changes balances, not in a uniform way"
Commenting on the results, Landbank Group CEO, Andreas Christoforides , MRICS, said, "The picture of the third quarter is not limited to the significant increase in recorded off - plan transactions. The greatest interest lies in the change in their distribution. Limassol strengthened its share in value, Paphos gained ground in the number of transactions, while Nicosia, despite the decline in its relative share, maintains a substantial presence in new developments."
At the same time, he added, almost two out of three sales concern properties under €300,000. "For developers, the message is clear: the right choice of area, property type and price category is decisive for the absorption of a project. The market is not uniform and cannot be evaluated only by the average price or the total number of sales," Mr. Christoforidis emphasized.
“In areas such as Germasogeia and Agios Tychonas, high values coexist with a particularly diverse transaction composition. Reliable analysis must combine volume, median value, sales range and product characteristics. This is the basis for better development and investment decisions,” pointed out the CEO of Landbank Group.
About Landbank Group
Landbank Group operates in Cyprus in the fields of real estate brokerage, property valuations and consultancy services and data analysis. Through Landbank Analytics, it provides evidence-based analysis of the Cypriot real estate market to investors, developers, banks and family offices. The company's Founder and CEO is Andreas Christoforidis, MRICS.
(Source: InBusinessNews)